There is a strange thing about retirement. For most of your working life, it feels miles away. You know it is coming eventually, but there is always something more immediate to deal with first. The mortgage needs paying, the car needs replacing, the kids need something, or there is simply another busy year to get through.
Then retirement starts feeling close enough to put a date on.
That is usually when the questions become harder to ignore. When can I actually stop working? What will I live on? Will I have enough left for travel? And perhaps the biggest one, what am I going to do with all that extra time?
There is plenty to think about, but it does not all have to be worked out at once.
Picture an Ordinary Tuesday
Forget the dream holiday for a minute.
Imagine an ordinary Tuesday a few years after you have finished work. You wake up and there is nowhere you have to be. What happens next?
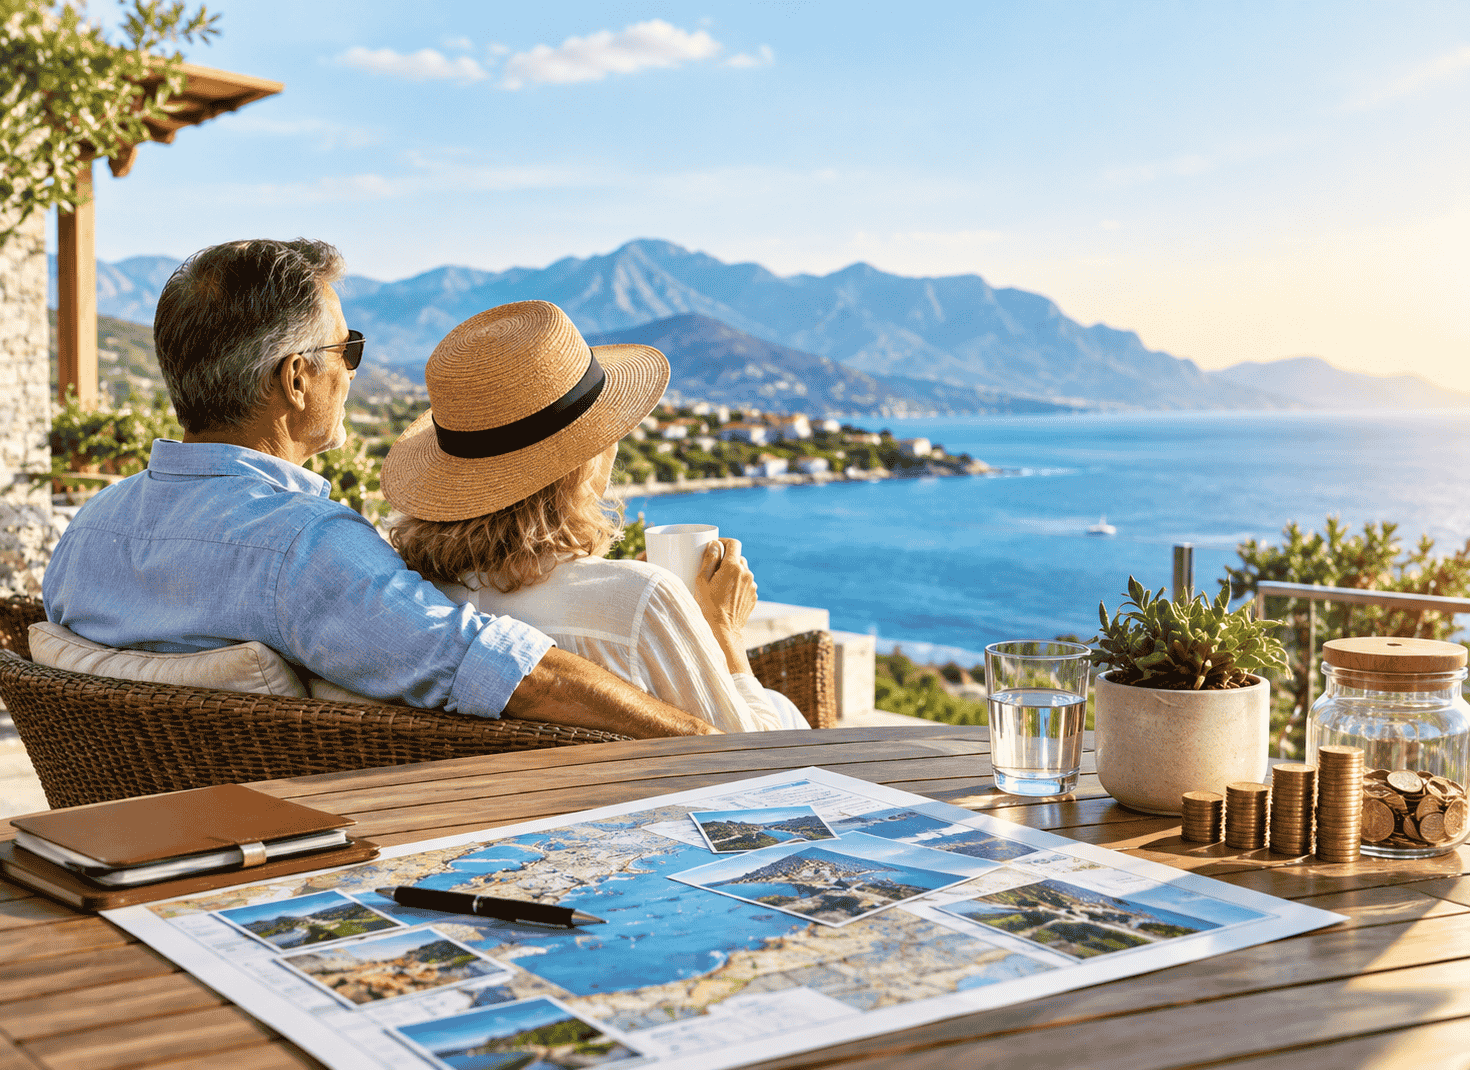
Maybe you walk the dog, meet someone for coffee and spend the afternoon in the garden. Perhaps you are picking up grandchildren from school. You might be halfway down the coast in a caravan. You could even still be doing a little work because you enjoy it, just without the five-day-week routine.
That ordinary Tuesday probably tells you more about the retirement you want than a generic savings target ever could.
It also gives you somewhere practical to start. Someone hoping to travel for several months every year is going to have different needs from someone who loves being at home.
Have a Proper Look at Your Money
This part is easy to put off.
Over the years, finances tend to become scattered. There is superannuation, money sitting in savings, the house, perhaps another investment, and bills coming from several directions. There might still be a mortgage hanging around too.
Sit down and look at the whole lot.
It does not need to become an enormous weekend project with twelve spreadsheets open on the kitchen table. Even a rough snapshot is useful. Write down what you own, what you owe and what you normally spend.
You may find things are better than you thought. You may spot something that needs attention. Either result is useful because at least you are dealing with what is actually there.
If the numbers start raising more questions than answers, getting help with retirement planning can be worthwhile, particularly when several financial decisions need to work together.
Your Current Spending Is a Good Clue
People sometimes imagine that the day they retire, their spending habits will completely change.
Some things certainly will. No commute means less petrol. Work clothes might stop appearing on the shopping list. Buying lunch near the office three times a week may disappear too.
But life does not suddenly become free.
You will still buy groceries. The electricity bill will keep arriving. The house will need repairs and the car will eventually need tyres. You may actually spend more on certain things simply because you finally have time to enjoy them.
Think about weekends now. What do you spend money on when you have a free day? Coffee? Lunch out? Gardening? Golf? A drive somewhere?
Retirement contains a lot more free days.
Looking at real spending gives you something far more useful than trying to create an unrealistically cheap version of your future life.
Leave a Little Room for Surprises
Nobody gets a perfectly predictable retirement.
A hot water system gives up. The family plans a wedding interstate. A friend suggests a trip you would hate to miss. Your ten-year-old car decides it has done enough.
Some surprises are frustrating. Others are exactly the kind of opportunities you hoped retirement would bring.
Either way, having some breathing room matters.
A plan that only works if nothing unexpected happens can quickly become stressful. You do not have to prepare for every imaginable expense, but it helps if an unplanned bill does not throw everything off course.
You Might Miss Work More Than Expected
People talk a lot about having enough money to retire. They talk less about what it feels like when Friday afternoon stops meaning anything.
Work creates routine without us noticing it. There is a reason to get dressed in the morning, people to talk to and a fairly predictable shape to the week.
Walking away from that can feel wonderful. It can also feel surprisingly odd.
That does not mean you need an ambitious retirement schedule. It might just mean having a few things that give the week some shape.
Maybe Wednesday becomes golf day. Friday is when you see the grandchildren. You volunteer twice a month or keep doing a little consulting work. Perhaps you finally join the local group you have been saying you would join for the past ten years.
Small routines can matter.
Plans Are Allowed to Change
You might decide at 55 that you want to retire at 65, then reach 62 and realise you are ready sooner. Or you might enjoy work enough to stay longer.
The same goes for everything else.
You could plan to travel constantly and discover after two big trips that you would rather be home. You might sell the family house, or decide you never want to leave it.
Changing your mind does not mean the original plan failed.
It simply means life moved on.
Give Retirement a Bit of Thought Now
You do not need to know exactly what you will be doing at 73.
You just need somewhere to begin.
Think about the Tuesday. Look at what you have. Be realistic about what you spend. Talk to your partner about what each of you actually wants.
Retirement is a big change, but it is also a chance to build a different kind of everyday life. Giving it some thought before the final day at work means you can spend less time wondering what comes next and more time enjoying the fact that, for once, Tuesday morning is completely yours.